Rockin Robin SongFlying The Web For News.


Consumer Daily Reports

The average 30-year mortgage rate held steady at 7.40% this week

By Mark Huffman Consumer News: Mortgage rates finally stop rising, but remain at a nearly three-year high of ConsumerAffairs
October 16, 2026
  • Mortgage rates held steady this week, with the average 30-year fixed-rate mortgage remaining at 7.40%, according to Freddie Mac.

  • The pause ended seven consecutive weeks of increases, but rates remain at their highest level since November 2023.

  • Housing affordability remains a major challenge, with higher borrowing costs, elevated home prices and economic uncertainty keeping many prospective buyers on the sidelines.


After nearly two months of steadily rising borrowing costs, prospective homebuyers finally got a break this week although it wasn't much of one.

The average interest rate on a 30-year fixed-rate mortgage remained unchanged at 7.40% for the week ending October 15, according to Freddie Mac's latest Primary Mortgage Market Survey. That matched last week's rate and ended a seven-week streak of increases.

Despite the pause, mortgage rates remain at their highest level in nearly three years. The last time rates were higher was November 16, 2023, when the average reached 7.44%.

A year ago, the average 30-year mortgage rate was just 6.27%, underscoring how dramatically borrowing costs have increased over the past 12 months.

The average rate on a 15-year fixed-rate mortgage, often used by homeowners refinancing an existing loan, edged lower to 6.71% from 6.73% last week. A year earlier, it averaged 5.52%.

What higher rates mean for homebuyers

The increase in mortgage rates has significantly reduced purchasing power, particularly for first-time buyers already struggling with elevated home prices.

Consider a buyer taking out a $350,000 mortgage. At this week's average rate of 7.40%, the monthly principal and interest payment would be approximately $2,423.

At the 6.27% average rate a year ago, that same loan would have required a monthly payment of about $2,160.

That's an increase of approximately $263 a month, or more than $3,100 a year, without accounting for property taxes, homeowners insurance or other housing expenses.

The increase also means some buyers who qualified for a mortgage a year ago may no longer qualify for the same loan amount.

Why mortgage rates remain elevated

Mortgage rates are closely tied to yields on 10-year U.S. Treasury bonds, which have risen sharply amid persistent inflation concerns, higher energy prices and uncertainty about future Federal Reserve interest rate decisions.

Although the Federal Reserve does not directly set mortgage rates, its monetary policy influences bond markets and lenders' borrowing costs.

Treasury yields have retreated somewhat after reaching multidecade highs, helping interrupt the recent rise in mortgage rates. However, inflation concerns continue to limit the potential for a sustained decline.

The higher rates are also weighing on mortgage demand. According to the Mortgage Bankers Association, mortgage applications declined 2.7% during the week ending October 9, marking the sixth consecutive weekly decrease.

Will mortgage rates fall anytime soon?

Prospective homebuyers hoping for a return to mortgage rates below 6% may face a long wait.

Fannie Mae's latest forecast projects the average 30-year fixed mortgage rate will remain at approximately 7.4% during the final quarter of 2026 before rising to an average of 7.5% in 2027.

The Mortgage Bankers Association also expects rates to remain above 7% next year, suggesting that today's elevated borrowing costs could persist well into the future.

Those forecasts are subject to change, particularly if inflation slows more quickly than expected or economic growth weakens.

For consumers planning to purchase a home, the latest numbers reinforce the importance of shopping around for a mortgage. Rates can vary considerably among lenders, and obtaining quotes from several companies could result in meaningful savings over the life of a loan.

Buyers should also consider the total monthly cost of homeownership, including insurance, property taxes and maintenance, rather than focusing solely on the interest rate.


Consumer News: Mortgage rates finally stop rising, but remain at a nearly three-year high

Photo By CNET


Posted: 2026-10-16 11:04:13

Get Full News Story On Consumer Affairs


More News From This Category
Consumer News: Consumer product safety recall roundup for October 16, 2026
Fri, 16 Oct 2026 16:07:08 +0000

Cooking tools, kids' accessories, and some food items are part of this week's recall roundup

By News Desk of ConsumerAffairs
October 16, 2026

Recall Roundup: New CPSC and FDA alerts

This roundup covers newly announced recalls and safety warnings from the Consumer Product Safety Commission and the Food and Drug Administration.

Primark recalls childrens coin purses

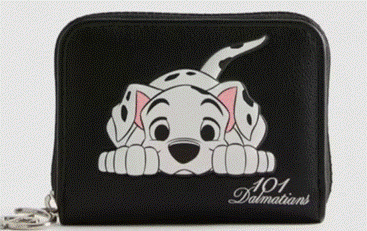
The recalled 101 Dalmatians faux leather coin purses contain phthalate levels above federal limits and should be returned for a refund.

  • The coin purses contain higher phthalate concentrations, creating a chemical exposure risk for young children, including through ingestion.
  • About 2,100 units were sold at Primark stores in the Northeast and in Florida, Maryland and Illinois from March 2026 through June 2026 for about $9.
  • Consumers should stop using the coin purses immediately, keep them away from children and return them to a Primark store for a full refund.
Product

Primark US Corp., of Boston, is recalling its Primark 101 Dalmatians Faux Leather Coin Purse, Model No. 2595301. The black purse has a picture of a dalmatian and 101 Dalmatians printed on the front, with the model number on a tag attached to the zip puller. The company says the product contains phthalate levels that exceed allowable limits.

The hazard

According to the CPSC, the coin purses contain elevated concentrations of phthalates. Those chemicals can be harmful if young children are exposed to sufficient amounts, including through ingestion, and certain phthalates have been linked to developmental effects and impacts on the hormone system. No incidents or injuries had been reported at the time of the recall.

What to do

Consumers should stop using the recalled coin purses right away and keep them out of childrens reach. Primark says shoppers should return the item to a Primark store to receive a full refund in the original form of payment.

Company contact

Primark can be reached at 617-946-3236 from 8 a.m. to 5 p.m. ET Monday through Friday, or online at www.primark.com/recall or www.primark.com by clicking Recalls at the bottom of the page.

Source


Kalorik air fryer ovens burn users

CPSC is warning consumers to stop using Kalorik MAXX air fryer ovens with French doors because the doors can suddenly close on users arms while the oven is on.

  • The spring-loaded French doors can suddenly shut on a consumers arms, creating a risk of serious burns.
  • The warning covers Kalorik MAXX and MAXX Advance ovens sold nationwide and online from April 2020 to Jan. 8, 2024, with additional sales after June 23, 2025.
  • Consumers should stop using the ovens immediately and dispose of them according to local hazardous waste procedures.
Product

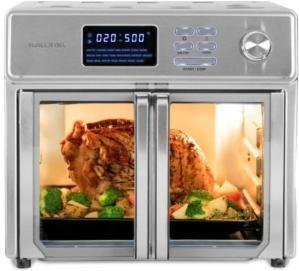
The CPSC issued a safety warning for Kalorik MAXX Air Fryer Ovens with French Doors, including MAXX and MAXX Advance models. The countertop ovens have a metal frame and spring-loaded bilateral glass doors with metal handles. Federal regulators say those doors can suddenly close on a users arms while the oven is operating.

The hazard

CPSC said its investigation found that the French doors can slam shut unexpectedly, exposing consumers to serious burn injuries while reaching into or working around a hot oven. The warning applies to products sold by Team International Group of America Inc. and Kalorik LLC from April 2020 to Jan. 8, 2024, and by The Legacy Companies LLC after June 23, 2025. The agencys notice did not list a recall remedy.

What to do

Consumers should stop using these ovens immediately. CPSC urges owners to dispose of the defective products following local hazardous waste disposal procedures rather than resell or continue using them.

Company contact

The warning directs consumers to report incidents involving Kalorik MAXX Air Fryer Ovens, or any product-related injury, to CPSC at SaferProducts.gov.

Source


Power Quick Pots pose burn risk

CPSC is warning consumers to stop using certain 6-quart Power Quick Pot pressure cookers because the lid can open while the cooker is still pressurized.

  • The pressure cookers lid can open while the unit is pressurized, allowing hot contents to erupt and cause serious burns.
  • The warning covers 6-quart Power Quick Pot electric pressure cookers, model Y6D-36, sold nationwide online from about July 2018 to November 2023 for $44 to $160.
  • Consumers should stop using the cooker immediately, dispose of it and not sell or give away the product.
Product

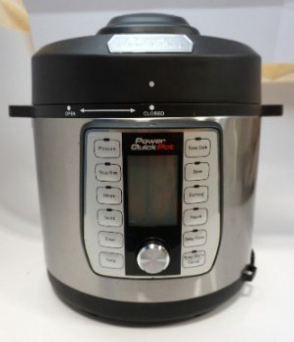
The CPSC is warning consumers to immediately stop using Tristar Products 6-Quart Power Quick Pot electric pressure cookers, model Y6D-36. The stainless-steel cookers have a black pressure lid, button controls, and a digital temperature and function display. Regulators say the lid can be opened while the contents remain under pressure.

The hazard

When a pressure cooker opens before internal pressure has safely dissipated, hot food and liquid can be expelled unexpectedly. CPSC said that failure creates a risk of serious burn injuries. The units were sold on Walmart.com, Amazon.com, Ebay.com and through other retailers nationwide over several years.

What to do

Consumers should stop using the recalled pressure cookers right away and dispose of them. CPSC also warns owners not to sell, donate or give away the hazardous product, which could put another household at risk.

Company contact

CPSC asks consumers to report any incidents involving injury or product defects at www.SaferProducts.gov.

Source


Argatroban injection recalled over particles

Par Health is recalling certain lots of Argatroban Injection after finding particulate matter that could trigger life-threatening complications if administered.

  • The injectable drug may contain cellulose, polystyrene, polyethylene terephthalate, stopper material and possibly stainless steel particles.
  • Affected lots were distributed nationwide to wholesalers and hospitals between Dec. 30, 2024, and May 5, 2026.
  • Wholesale distributors and hospital pharmacies should stop using and distributing affected lots immediately and arrange returns through Inmar.

Par Health has announced a voluntary nationwide recall of Argatroban Injection 250 mg/2.5 mL (100 mg/mL). The affected product was distributed at the hospital and user level, with impacted lots sent nationwide to wholesalers and hospitals. The company said the recall was triggered by the presence of particulate matter in some vials.

The hazard

According to the FDA notice, the particles identified include cellulose, polystyrene, polyethylene terephthalate, stopper material and possibly stainless steel. If administered, contaminated injections have a reasonable probability of causing life-threatening adverse health consequences, including pulmonary emboli, blockages of other blood vessels that can lead to tissue death and organ damage, and inflammation of vein walls that may lead to clotting.

What to do

Par Health said wholesale distributors and hospital pharmacies with the affected lots should immediately discontinue use and stop distribution. The company is notifying accounts in writing and arranging for the return of remaining inventory through Inmar Inc.

Company contact

Consumers can contact Inmar Inc. at 1-855-648-7909. Media inquiries should be directed to Gena Holthaus, senior director of corporate brand and communications, at media.relations@parhealth.com.

Source


Pan Pepin recalls Para Bien Al Grano

Pan Pepin Inc. is recalling Para Bien Al Grano products distributed in Puerto Rico because sesame was not declared on the label.

  • The product may contain undeclared sesame, posing a serious or potentially life-threatening allergy risk.
  • The affected packages were distributed throughout Puerto Rico and include UPC 0 21425 01513 4 with specified sell-by and lot codes.
  • Consumers with a sesame allergy or sensitivity should not consume the product and should return it for a full refund or dispose of it if returning it is not possible.

Pan Pepin Inc. has issued an allergy alert for Para Bien Al Grano due to undeclared sesame. The recalled product was distributed throughout Puerto Rico and is identified by UPC 0 21425 01513 4 and multiple affected sell-by and lot codes. People with a sesame allergy or severe sensitivity face the greatest risk.

The hazard

Sesame is a major allergen, and consuming a product that does not disclose it on the label can trigger a serious or life-threatening allergic reaction. The FDA notice lists the affected lots as Sell By Oct / 12 3B1 274, Oct / 14 3B1 277, Oct / 15 3B1 278, Oct / 17 3B1 280, Oct / 18 3B1 281, Oct / 19 3B1 282, and Oct / 21 3B1 284.

What to do

Consumers who have a sesame allergy or sensitivity should not eat the product. Pan Pepin says shoppers should return the recalled item to the place of purchase for a full refund, or discard it if a return is not possible.

Company contact

Pan Pepin Inc. can be reached at 787-403-7363 or by email at luis.santini@panpepin.com.

Source


Oliva dips recalled for sesame

Oliva LLC is recalling select Baba Ghanouj and hummus products sold in parts of Connecticut and Massachusetts because sesame was not declared.

  • The dips may contain undeclared sesame, which can cause serious or life-threatening allergic reactions.
  • The recall covers Riads Oliva to Go Baba Ghanouj, Spicy Baba Ghanouj, and Hummus with listed best-by dates sold in Litchfield County, Connecticut, and Great Barrington, Massachusetts.
  • Consumers should return the products to the place of purchase for a full refund or replacement.

Oliva LLC has issued an allergy alert covering Riads Oliva to Go Baba Ghanouj, Spicy Baba Ghanouj, and Hummus. The recalled products were distributed to gourmet shops and farm markets in Litchfield County, Conn., and the Great Barrington, Mass., area. The company said the products contain undeclared sesame allergen.

The hazard

For people with a sesame allergy or severe sensitivity, eating these products could trigger a serious or life-threatening allergic reaction. The affected items carry best-by dates including 10/10/26 through 10/14/26, 10/10-26 through 10/14/26, and 10/12/26 through 10/18/26, according to the FDA notice.

What to do

Consumers who purchased the recalled dips should not consume them if they have a sesame allergy or sensitivity. Oliva says the products should be returned to the place of purchase for a full refund or a replacement.

Company contact

For more information, consumers can call 203-266-5558.

Source


Consumer product safety recall roundup for October 16, 2026

Photo By CNET

Read More ...


Consumer News: Could this Sardinian village hold clues to living longer?
Fri, 16 Oct 2026 16:07:08 +0000

Researchers uncover a surprising longevity pattern in a small Italian community

By Kristen Dalli of ConsumerAffairs
October 16, 2026
  • Women in Bolotana, Sardinia, were more likely to reach 100 than women in Italy or the United States.

  • Researchers verified residents ages using historical civil records and church archives.

  • Walking, locally grown food, and strong family connections could offer clues, but more research is needed to explain the villages longevity.


What if the secrets to a longer life could be hiding in a small Italian village?

Researchers studying Bolotana, a mountain community on the island of Sardinia, have found an unusual pattern of longevity that could make it a new destination for researchers exploring why some people live longer than others.

The study, published in Frontiers in Aging, found that women in Bolotana who reached age 70 had an estimated 13.8% chance of living to 100. That compares with approximately 3.5% for women across Italy and 3.6% for women in the United States.

The findings suggest Bolotana could be a new blue zone, a term used to describe places where residents experience unusually long lives. However, researchers caution that more evidence is needed before the village can officially be considered an established longevity hotspot.

What makes Bolotana extraordinary is that it has an incredible historical record that allows us to definitively evaluate ages at birth and death, researcher S. Jay Olshansky said in a news release. The municipal and baptismal records date back centuries and allowed us to independently verify ages.

How researchers investigated longevity

To determine whether Bolotana's reputation for long life was supported by the numbers, researchers examined demographic data covering 2021 through 2025. They focused on two measures: how many additional years people could expect to live after turning 70 and the likelihood of surviving from age 70 to age 100.

The team compared its findings with data from Sardinia's surrounding Nuoro province, the island as a whole and Italy nationally. Researchers also compared Bolotana with established longevity benchmarks, including Sardinia's original blue zone.

Accurate age records were especially important. Researchers cross-checked municipal birth and death records against historical church documents, including baptismal and burial records. They verified the ages of all identified centenarians, helping address concerns that unusually old ages can sometimes result from inaccurate documentation.

The researchers also examined alternative time periods to see whether their findings held up under different assumptions.

What the findings could mean for consumers

Women in Bolotana stood out in the results. Those who reached age 70 had an estimated 20.85 additional years of life expectancy, while their chances of reaching 100 were more than three times those of women in the United States.

So, what might explain this pattern? The study did not establish a cause, but the village offers several possibilities worth investigating. Residents live in a walkable community with steep streets and hills, many foods are grown locally, and family members often live near one another. Social isolation also appears to be uncommon.

Researchers believe physical activity, diet, family support, social connections, and genetics may all play a role. Still, the results varied depending on the years examined, and the team says further observation is necessary.

For consumers, the findings offer a reminder that longevity may involve more than any single food, supplement, or fitness routine. Everyday movement and meaningful social connections are potential areas for further study, but this research does not prove that adopting any one habit will help someone live to 100.

If we can identify the characteristics behind this longevity and help people adopt them, the rest of the world can benefit from understanding the values practiced by these communities, Olshanksky said.

Read More ...


Consumer News: Frequent daytime napping may signal higher dementia risk, study finds
Fri, 16 Oct 2026 16:07:08 +0000

Unplanned naps were linked to a greater likelihood of dementia in older adults

By Kristen Dalli of ConsumerAffairs
October 16, 2026
  • Older adults who napped most days or every day had a 48% higher risk of developing dementia than those who rarely or never napped.

  • Falling asleep unintentionally during the day was associated with a 39% higher risk of dementia.

  • Researchers say the findings don't prove that napping causes dementia, but changes in sleep habits could offer an early warning sign.


Taking a nap during the day might seem like a harmless way to recharge, especially as people get older. But new research suggests that how often older adults nap and whether they intend to fall asleep could offer clues about their future brain health.

A study from the Johns Hopkins Bloomberg School of Public Health found that frequent and unintentional daytime napping were associated with a higher risk of developing dementia among older adults. The findings suggest that daytime sleep patterns may deserve more attention when researchers study cognitive health and dementia risk.

However, the results don't mean that taking a nap will cause dementia. Researchers say excessive daytime sleepiness could also reflect changes in the brain that occur before dementia is diagnosed.

More frequent napping could be a marker of changes in the brain, rather than a cause of brain changes that lead to dementia, researcher Adam Spira, Ph.D., M.A., said in a news release.

How researchers studied napping and dementia risk

The study, published in The Journals of Gerontology: Series A, examined data from 995 U.S. adults ages 65 and older who participated in the National Health and Aging Trends Study. None had possible or probable dementia when researchers began tracking their napping habits in 2013.

Researchers followed participants through 2023, examining whether they developed possible or probable dementia over the study period. They compared participants' napping frequency, whether their naps were intentional or unintentional, and how long they typically slept during the day.

The researchers also accounted for other factors that could influence dementia risk, including participants' demographic backgrounds, health conditions, nighttime sleep duration, daytime sleepiness, and risk of obstructive sleep apnea.

Dementia status was determined using a validated classification method rather than a clinical diagnosis for every participant. Because the research was observational, it could identify associations between napping and dementia but could not establish cause and effect.

What the findings mean for older adults

The results showed that participants who napped most days or every day had a 48% higher risk of developing dementia than those who rarely or never napped. Those who unintentionally fell asleep during the day had a 39% higher risk.

Nap duration also mattered. Napping for 30 minutes or less was associated with a 40% higher risk of dementia. For naps lasting longer than 30 minutes, however, the association weakened after researchers accounted for nighttime sleep characteristics.

The researchers also conducted an additional analysis that excluded dementia cases identified during the first five years of follow-up. The association between frequent napping and dementia remained, suggesting that the pattern may appear years before a diagnosis.

Still, the findings shouldn't be interpreted as a reason to avoid naps altogether. Researchers say changes in brain regions responsible for keeping people awake could contribute to increased daytime sleepiness, meaning frequent napping might be an early sign of underlying changes rather than their cause.

For consumers, the key takeaway is to pay attention to changes in sleep habits, particularly if daytime sleepiness becomes frequent or naps happen without intending to fall asleep. More research is needed to determine whether changing napping habits could actually help prevent or delay dementia.

Monitoring napping behaviors could serve as an early and accessible marker to help identify older adults at higher risk for dementia and guide targeted interventions for dementia prevention, researcher Kening Jiang, Ph.D., said in the release.

Read More ...


Consumer News: Your pumpkin spice drink could pack more caffeine than 3 Red Bulls — here's what to know
Fri, 16 Oct 2026 16:07:07 +0000

Some popular fall drinks deliver a surprising caffeine kick, even compared with regular coffee and energy drinks

By Kyle James of ConsumerAffairs
October 16, 2026
  • Pumpkin packs a punch: Some seasonal Starbucks drinks contain more caffeine than three small cans of Red Bull.

  • Not all fall drinks are equal: A pumpkin spice latte, cold brew, and shaken espresso can have dramatically different caffeine levels.

  • Know your limit: The FDA says 400 milligrams of caffeine per day is generally safe for most healthy adults, although individual sensitivity varies.


Pumpkin spice season is officially here.

And while you're sipping that delicious pumpkin-flavored drink, enjoying the fall weather, and pretending it's sweater season, you might be getting a whole lot more caffeine than you realize.

In fact, some popular fall drinks contain surprisingly more caffeine than two or even three cans of Red Bull. That's quite a jolt for something that tastes like pumpkin pie.

A recent ranking of caffeinated fall drinks highlights just how much caffeine can hide behind those seasonal flavors.

So how do your favorite pumpkin drinks compare with regular coffee and energy drinks?

How much caffeine is hiding in your favorite fall drinks?

First, a little perspective.

A regular eight-ounce cup of brewed coffee contains approximately 95 milligrams of caffeine, while a standard 8.4-ounce can of Red Bull contains 80 milligrams.

Now, let's see how some popular Starbucks fall drinks stack up. All amounts are for a grande (16 ounces).

  • Iced Pumpkin Cream Shaken Espresso: A whopping 255 mg of caffeine. That's more than three Red Bulls or nearly three regular cups of coffee.

  • Pumpkin Cream Cold Brew: With 185 mg, you're getting more than two Red Bulls worth of caffeine.

  • Pumpkin Spice Latte: This fall favorite packs 150 mg of caffeine, or nearly two Red Bulls in one cup.

  • Pumpkin Spice Frappuccino: Even this dessert-like drink has 100 mg of caffeine, which is slightly more than a regular cup of coffee or a small Red Bull.

Of course, caffeine amounts can vary depending on the drink's size and how it's prepared.

But the big takeaway? Don't let the pumpkin flavor, whipped cream, or sweet toppings fool you.

Some of these drinks deliver a serious caffeine kick.

The biggest surprise? That shaken espresso

Let's talk about the Iced Pumpkin Cream Shaken Espresso.

At 255 milligrams of caffeine, a grande contains nearly two-thirds of the FDA's suggested daily caffeine benchmark for most healthy adults.

And that's before you factor in the coffee you had with breakfast.

For example, drink one regular cup of coffee in the morning and grab that pumpkin shaken espresso in the afternoon, and you're already at approximately 350 milligrams of caffeine. Add another cup of coffee, and you've exceeded 400 milligrams.

That doesn't automatically mean you're in danger, but it does mean you might be consuming more caffeine than you intended.

4 ways to enjoy fall drinks without the caffeine overload

You don't have to give up pumpkin spice season. Just order a little smarter.

  1. Don't assume sweet means weak. Pumpkin foam, whipped cream, and sugary syrups can make a strong coffee drink taste more like dessert. Check what's underneath all those toppings.

  2. Check the caffeine before ordering. A larger drink doesn't always mean proportionally more caffeine. Some sizes contain additional espresso shots, while others simply have more milk. Look up the caffeine content for your exact drink and size.

  3. Ask about decaf. If you love the taste of a pumpkin spice latte but don't need the afternoon energy boost, ask whether it can be made with decaf espresso. Just remember that decaf isn't completely caffeine-free.

  4. Count all your caffeine, not just your coffee. Energy drinks, soda, tea, and even some medications can add to your daily total.

According to the FDA, too much caffeine can cause jitters, anxiety, headaches, nausea, and trouble sleeping.

And some people are much more sensitive to caffeine than others.

The bottom line

There's nothing wrong with treating yourself to a pumpkin spice latte this fall.

But before you order that second seasonal drink, remember that a cozy fall beverage can pack the caffeine equivalent of several energy drinks.

Sometimes that pumpkin-flavored pick-me-up comes with a much bigger wake-up call than you bargained for.

Read More ...


Consumer News: A powerful El Niño could be coming — 5 things homeowners should do now
Fri, 16 Oct 2026 16:07:07 +0000

An insurance expert says a few simple steps now could save thousands later

By Kyle James of ConsumerAffairs
October 16, 2026
  • A potentially powerful El Nio is developing: NOAA says there's more than an 83% chance of a strong-to-very strong El Nio lasting into early 2027.

  • Your homeowners insurance may have major gaps: Standard policies generally don't cover flooding, and separate flood insurance typically takes 30 days to become effective.

  • A little preparation can go a long way: Reviewing your policy, documenting your belongings, and checking your home's drainage could help prevent expensive surprises.


A potentially historic El Nio is taking shape, and homeowners may want to spend a little time preparing before winter storms arrive.

NOAA's latest forecast puts the odds of a strong-to-very strong El Nio lasting into early 2027 at more than 83%. And even if you have homeowners insurance, some types of storm damage might not be covered.

Tom McLaughlin, founder and CEO of Finch, a platform that helps public insurance adjusters analyze property claims, says homeowners should use the coming weeks to get ahead of potential problems.

"A storm season this well forecast is a rare head start," McLaughlin told ConsumerAffairs.

Here are five things he recommends doing now.

1. Find out what your homeowners insurance actually covers

This might be the most important 15 minutes you spend preparing for winter.

Pull up your homeowners insurance policy and look specifically for exclusions involving flooding, mudflow, landslides, and earth movement.

"A lot of people think they're covered for things they're not," McLaughlin said.

For example, a standard homeowners insurance policy generally doesn't cover flood damage. And while certain types of mudflow may qualify for coverage under flood insurance, landslides generally don't.

What to do: Call your insurance agent and ask a simple question: "If heavy rain causes water or mud to damage my house, exactly what would my policy pay for?" Then be sure to ask for the answer in writing.

2. Don't wait until a storm is coming to buy flood insurance

Here's a detail that could cost homeowners thousands: Most standard homeowners policies don't cover flooding. And a separate policy through the National Flood Insurance Program typically has a 30-day waiting period before coverage begins.

So, if you end up waiting until a major storm is in the forecast to get coverage, it may already be too late.

Now its worth mentioning that there are some exceptions to the waiting period, including certain mortgage-related purchases, so ask your agent about that.

What to do: Visit FloodSmart.gov to learn about coverage and find an insurance provider. You can also ask your agent about private flood insurance, which may offer different coverage limits and waiting periods.

3. Make a 20-minute video of your entire house

This might be the easiest tip on the list, and it costs absolutely nothing.

McLaughlin recommends taking your smartphone and walking through every room, recording furniture, electronics, appliances, and other valuables.

Don't forget the garage, exterior of your home, and any expensive equipment. Then upload the footage to cloud storage so you can access it even if your phone is damaged or lost.

Finch says it has analyzed more than 15,000 insurance claims, and McLaughlin says homeowners who documented their property beforehand generally had a much easier time settling their claims.

What to do: Record one continuous walkthrough, then take close-up photos of expensive items, serial numbers, and receipts if possible. This is just a smart practice, as itll help with other potential issues like theft and fire damage.

4. Check these three things outside your house

You don't necessarily need to spend hundreds of dollars getting ready for a wet winter.

McLaughlin recommends starting with three relatively simple maintenance tasks:

  • Clean your gutters: Remove leaves and debris so rainwater can flow freely.

  • Check drainage: Make sure downspouts carry water away from your foundation and that the ground slopes away from the house.

  • Inspect your roof: Take a close look for any missing or lifted shingles, and have a professional handle any repairs.

What to do: Walk around your home during the next rainfall and look for overflowing gutters or water pooling near the foundation. At that point you can fix any problems before the next major storm.

5. Check how much your insurance would actually pay

Being covered doesn't necessarily mean you'll receive enough money to replace everything you lose.

McLaughlin says homeowners should understand the difference between two common insurance terms:

  • Actual cash value: This is when your insurance company factors in the age and condition of your damaged property when determining how much money you'll receive.

  • Replacement cost: Your insurance company covers the cost of replacing damaged property with a comparable new item, subject to your deductible and policy limits.

For example, consider a television that originally cost you $1,500, but is now worth only $400 because of its age. An actual cash value policy will give you about $400 for the TV, while replacement cost coverage would give you enough money to get a similar new TV.

What to do: Check whether your dwelling and personal belongings have replacement cost coverage, and ask your agent about your deductible and coverage limits.

One last tip if you ever have to file a claim

McLaughlin also recommends keeping a written record of every conversation with your insurance company.

In an analysis of 900 California claims, Finch found that a typical claim involved at least three different insurance company adjusters. That can mean explaining your situation repeatedly.

His advice? After every phone call, send a short follow-up email documenting what was discussed and any agreements reached. It creates a paper trail that could prove valuable if questions or disputes arise later.

The bottom line: You obviously can't control what El Nio might bring this winter. So its smart to focus on the things you can control.

Specifically, you can spend an afternoon making sure your insurance is adequate, your property is documented, and your house is better prepared for whatever comes next.

Read More ...


Related Bing News Results
Consumer Reports found Nissan’s Rogue and Frontier could sell for 16% or more below sticker with negotiation and rebates
Fri, 16 Oct 2026 03:35:00 GMT
Two Nissan models sit at the top of Consumer Reports’ latest roundup of discounted, recommended 2026 vehicles: the Rogue AWD SV and the Frontier Crew Cab 4×2 Long Bed SV, each carrying potential ...
Consumer Reports Labels, Explained: Recommended, Top Pick, Best Brand, Best of, Smart Buy, and #1 in Brand Reliability
Thu, 15 Oct 2026 03:00:00 GMT
Consumer Reports (CR) uses several designations to help shoppers quickly identify products and services that perform well in our independent evaluations. When data is available, these designations ...
Consumer Reports Launches New ‘#1 in Reliability’ Badge to Help Shoppers Find Long-Lasting Kitchen Appliances
Thu, 15 Oct 2026 03:00:00 GMT
Consumer Reports (CR), the 90-year-old nonprofit research, testing, and advocacy organization, today introduced the #1 in Brand Reliability designation for kitchen appliances, which recognizes brands ...
Consumer Reports investigation: Testing shows most prenatal vitamins are inaccurately labeled
Fri, 09 Oct 2026 10:41:00 GMT
Prenatal vitamins are often one of the first things people start taking when they find out they’re pregnant. They can help provide important nutrients needed during pregnancy and support a baby’s ...
Consumer Reports wants FDA official to explain the agency's response to the Cyclospora outbreak
Wed, 14 Oct 2026 17:05:00 GMT
Consumer Reports has asked the FDA’s deputy commissioner to respond to its concerns about the agency’s response to this summer's Cyclospora outbreak linked to Taylor Farms lettuce from Mexico. In the ...

Blow Us A Whistle


RobinsPost Print On Demand Refund Policy With Printify
Printify

Related Product Search/Búsqueda de productos relacionados

Amazon Logo