Cybercriminals are sending a new wave of sextortion emails claiming they have complete access to victims' computers, phones, and online accounts.
The scammers often include an old password obtained from a previous data breach to make their threats appear legitimate.
Security experts say the threats are almost always fake and victims should not pay the cryptocurrency ransom being demanded.
If a scam is effective, you can bet it will be tried time and time again. Cybersecurity firm Malwarebytes warns that consumers are once again being targeted by a familiar but effective online extortion scheme.
In a consumer alert, the company reports a resurgence of so-called sextortion emails, claiming hackers have gained complete control of victims' devices.
The emails typically allege that the sender installed malware on the recipient's computer through a browser vulnerability or malicious website. The scammer claims to have full access to the victim's files, email accounts, contacts, webcam, and microphone, and threatens to release embarrassing videos or private information unless a ransom is paid in cryptocurrency.
Why threats may seem real
To make the threat seem credible, many of the messages include an actual password associated with the recipient. However, Malwarebytes says these passwords generally come from old data breaches and are unrelated to any current compromise of the victim's devices.
One recent version of the scam claims the victim's browser was infected through a "drive-by exploit" that allegedly provided the attacker with complete control over the device. The email then demands payment in Bitcoin within a few days, threatening to distribute compromising material to family members, friends, and social media contacts if the victim refuses.
Security researchers say the messages rely on fear, embarrassment, and urgency rather than actual hacking. In many cases, scammers send the same email to thousands of people, hoping a small percentage will panic and pay.
What not to do
Malwarebytes advises consumers not to respond to the emails, not to send any money, and not to click on attachments or links contained in the messages. Recipients who recognize a password included in the email should immediately change it if they are still using it on any account.
Experts also recommend enabling multi-factor authentication, using unique passwords for every account and monitoring for signs that personal information may have been exposed in a data breach.
The scam's persistence reflects the continuing profitability of sextortion schemes. Researchers have found that such campaigns can generate substantial revenue for cybercriminals despite their relatively simple tactics.
Consumers who receive one of these emails should remember that the presence of a real password does not mean a hacker currently controls their devices. In most cases, cybersecurity experts say, the message is simply another attempt to turn old stolen data into a new payday.
Dealers have millions of new vehicles in stock, but fewer freshly designed models to show shoppers.
Inventory is uneven: affordable cars and some popular brands are relatively scarce, while certain higher-priced vehicles are plentiful.
For buyers, the best bargaining opportunities may be on slow-selling models and outgoing model years.
A shopper walking into a dealership this fall may find rows of new vehicles but little that feels new. That is the distinction behind a seemingly contradictory picture of the auto market: Some dealers have more vehicles than they can readily sell, yet they say they need fresh models to attract customers.
The Wall Street Journal reports that automakers are introducing fewer newly designed vehicles, leaving dealers to sell familiar designs at higher prices. The shortage it describes is principally one of new model launches and redesigns, rather than a nationwide lack of unsold cars.
The inventory numbers bear that out. Cox Automotive counted 2.68 million new vehicles available at the end of August, enough to last 73 days at the recent sales pace. Cox said overall supply remained adequate, even after inventory declined for a third consecutive month.
But the national average hides large differences. Toyota had just 33 days of supply, while Stellantis brands, Buick and Lincoln carried some of the highest inventories. Vehicles priced at $30,000 or less had 54 days of supply; those priced above $60,000 had more than 90. A buyer looking for an affordable car may therefore face limited choices while another dealer is eager to move a more expensive vehicle.
Sales figures present a similarly mixed picture. Cox expects third-quarter sales volume to be lower than a year earlier, but forecasts September sales to rise 6.5% from last September. It recently raised its full-year forecast from 15.8 million to 16.1 million vehicles, citing stronger demand than it had expected.
What it means for automakers
Fresh designs give shoppers a reason to visit a showroom and can help an automaker compete without relying as heavily on discounts. When launches slow, dealers may be left trying to sell aging vehicles against newer offerings from rival brands. That can put pressure on manufacturers to offer incentives on models that linger, even as popular vehicles continue to sell with less help.
A new model year does not necessarily solve the problem: A 2027 vehicle may differ only modestly from its 2026 counterpart. The transition is running slowly, too. At the end of August, 2027 models made up 12.4% of available inventory, compared with a 23% share for 2026 models at the same point last year.
What it means for shoppers
Buyers should expect deals to depend heavily on the specific vehicle. A slow-selling model or an outgoing model year may offer room to negotiate. An affordable model with a short supply may offer much less. Comparing prices and financing offers across several dealers will be more useful than assuming that either shortage or glut describes the whole market.
Price remains a hurdle regardless of inventory. Kelley Blue Book put the average amount paid for a new vehicle at just over $50,000 in August. For shoppers who do not need the latest styling or features, an older design could still be a good buy if its price, equipment and total financing cost are right.
U.S. home prices rose 1.4% from a year earlier in August and 0.2% from July, according to First American Data & Analytics.
Annual price growth has stayed below its pre-pandemic average of 3.4% for 17 straight months.
The national figure hides sharp differences: prices rose 5.5% in Chicago but fell 5.0% in Dallas.
The rapid rise in U.S. home prices has slowed, but that does not mean homes have become cheap. Prices were 1.4% higher in August than a year earlier, according to First American Data & Analytics latest Home Price Index. They also rose 0.2% from July.
Annual growth has remained below the companys nearly three-decade, pre-pandemic average of 3.4% for 17 consecutive months. Even so, August prices were approximately 80% above their average for the same month during the five years before the pandemic, First American said. Slower growth offers prospective buyers some relief from rapid price increases, but it has not erased the earlier surge.
First American Chief Economist Mark Fleming attributed the subdued national pace to forces pulling in opposite directions. Higher mortgage rates are holding back buyers, while homeowners reluctant to give up lower-rate mortgages are limiting the supply of homes for sale.
The result, he said, is relatively steady but modest price growth.
Where prices are rising and falling
Conditions vary considerably by location. Among the 50 largest metropolitan markets covered by the index, Chicago posted the strongest annual gain in August at 5.5%. Hartford, Connecticut, followed at 5.3%, and New York at 5.2%.
Dallas recorded the largest decline, with prices down 5.0% from a year earlier. Prices also fell in Austin, Texas, by 3.4%; San Antonio by 2.9%; and Tampa, Florida, and Denver by 1.9% each. Fleming described the declines in several Sun Belt and Western markets as a rebalancing after years of rapid gains.
The picture also differs by price range. Prices for homes in the least expensive third of their local markets rose 5.5% in Cleveland and 5.3% in Philadelphia. Those gains matter particularly to first-time buyers looking for lower-priced homes, even as national price growth cools.
For buyers and sellers, the national average is only a starting point. A buyer in a market with falling prices may have more room to negotiate, while someone shopping in a city with strong gains could still face rising costs. First Americans latest index figures are preliminary and may change as more transactions are recorded.
WeightWatchers says growing consumer interest in GLP-1 weight-loss drugs is contributing to declines in its traditional diet business.
Medifast, owner of OPTAVIA, saw annual revenue plunge 36% in 2025 as it struggled to recruit customers and coaches in a market transformed by GLP-1 drugs.
Instead of trying to compete with the medications, traditional weight-loss companies are increasingly incorporating them into their businesses.
In April 2005, the U. S. Food and Drug Administration approved Byetta, the first GLP-1 drug, for the treatment of type 2 diabetes. Twelve years later, the FDA approved Ozempic (semaglutide), sending shockwaves through the weight-loss industry.
Companies that for decades made money helping consumers shed pounds through dieting, meal plans, coaching and behavior modification have in recent years confronted a new competitor: prescription medications that can produce substantial weight loss.
Financial results from WeightWatchers and Medifast provide some of the clearest evidence of the disruption.
WeightWatchers said its traditional Behavioral subscription revenue fell 15.2% in 2025, to $592.6 million from $699 million a year earlier. The number of Behavioral subscribers at the end of the year declined nearly 19%, to about 2.63 million.
At the same time, the part of WeightWatchers that embraces prescription weight-loss medications is moving in the opposite direction.
Clinical subscription revenue, which includes WeightWatchers Clinic and access to medications for eligible patients, increased nearly 45% in 2025, to $112.8 million. Clinical subscribers at the end of the year increased about 42% to 130,200.
The contrast illustrates how dramatically drugs known as GLP-1 receptor agonists are altering the economics of weight loss.
WeightWatchers acknowledges the shift
WeightWatchers executives aren't being subtle about what is happening.
"Our industry is undergoing a profound transformation driven by GLP-1 medications," CEO Tara Comonte said when the company reported its 2025 results.
Fourth-quarter revenue declined 12% from the previous year, which WeightWatchers attributed in part to increasing consumer interest in GLP-1 medications, along with longer-term pressure on its Behavioral business and the effects of its Chapter 11 financial reorganization.
The company filed for Chapter 11 bankruptcy protection in May 2025 and emerged the following month after restructuring its debt.
It would be an oversimplification to blame WeightWatchers' financial problems entirely on Ozempic, Wegovy and other drugs. The company had substantial debt and its traditional business had faced challenges for years.
But GLP-1 drugs have accelerated a fundamental change in what many consumers are looking for when they want to lose weight.
WeightWatchers is responding by becoming, in part, a medical weight-management company. Its Clinical operation gives eligible members access to clinicians and FDA-approved weight-loss medications. By the fourth quarter of 2025, Clinical revenue represented 17% of subscription revenue, compared with 11% a year earlier.
Medifast has been hit even harder
The numbers at Medifast, which operates the OPTAVIA weight-management program, are perhaps even more striking.
Medifast generated nearly $1.6 billion in revenue in 2022. By 2024, revenue had fallen to $602.5 million, and in 2025 it dropped another 36% to just $385.8 million. The company recorded a $18.7 million net loss for 2025.
The number of active earning OPTAVIA coaches fell to 16,100 at the end of 2025, down more than 40% from 27,100 a year earlier. Medifast said difficulties acquiring customers reflected broader market challenges, including the rapid adoption of GLP-1 medications for weight loss.
In regulatory filings, Medifast has described the weight-loss market as being "fundamentally impacted" by the rapid acceptance of GLP-1 medications.
That is forcing the company to rethink what it sells.
Medifast has partnered with telehealth provider LifeMD to give eligible OPTAVIA customers access to clinicians and weight-loss medications. It has also introduced nutrition plans and products specifically designed for consumers using GLP-1 drugs. By the end of 2024, about 44% of OPTAVIA coaches were already supporting at least one customer taking a GLP-1 medication.
Not every diet company has been devastated
The impact isn't uniform.
Herbalife, which sells weight-management products as part of a much broader nutrition business, reported worldwide sales of about $5.04 billion in 2025, up 0.9% from 2024. Its North American sales, however, declined 2%.
That suggests companies with diversified product lines and international businesses may be better insulated than companies whose fortunes depend primarily on Americans signing up for weight-loss programs.
Perhaps the clearest indication of how much the market has changed is that diet companies are no longer simply trying to compete against GLP-1 drugs. They're trying to make money from them.
WeightWatchers now combines its traditional behavioral program with clinical care and prescription medications. Medifast offers products for people taking GLP-1 drugs and provides access to clinicians through its partnership with LifeMD.
The strategy reflects an important reality: consumers taking weight-loss medications may still need nutritional guidance, exercise programs and help maintaining weight loss.
For traditional diet companies, that could provide a way forward. Instead of selling consumers an alternative to weight-loss drugs, they can sell services that complement them.
The financial numbers suggest that transition is already underway. At WeightWatchers, traditional Behavioral subscription revenue fell 15% last year while Clinical revenue jumped nearly 45%.
For an industry built for decades around the proposition that consumers could lose weight primarily by changing what and how much they eat, GLP-1 medications have introduced a fundamentally different proposition and some of the industry's biggest names are now racing to adapt.
The IRS is warning taxpayers about promoters selling nonexistent Tribal Tax Credits that supposedly reduce federal taxes or produce large refunds.
Promoters may claim the credits are backed by tribal governments or federal agreements, but the IRS says no such federal tax credits exist.
Taxpayers who put the bogus credits on their returns can be liable for unpaid taxes, interest and penalties and, in serious cases, could face criminal prosecution.
The Internal Revenue Service is warning consumers about a tax scheme that uses the names of Native American tribes and legitimate federal programs to make nonexistent tax credits appear real.
In a taxpayer alert, the IRS said promoters are marketing what they call Tribal Tax Credits, Native American Tax Credits or Sovereign Tribal Tax Credits. Despite the official-sounding names, the agency says there is no federal tax credit fitting those descriptions.
The promoters typically encourage taxpayers to buy the purported credits from an organization they claim is connected with a tribal community. The credits are then promoted as a way to reduce an existing federal tax bill or generate a refund.
In some cases, promoters promise taxpayers a substantial return on their investment and use high-pressure sales tactics to persuade them to act quickly, the IRS said.
The danger for consumers is that even if a promoter prepares the paperwork, taxpayers remain responsible for what's on their tax returns.
The IRS said a return claiming a nonexistent Tribal Tax Credit contains a false claim even if the agency initially processes the return and issues a refund. Participating in an abusive tax scheme can result in taxpayers having to repay taxes, along with interest and penalties. More serious cases can potentially result in fines or imprisonment.
Making a fake credit look legitimate
The schemes can be convincing because promoters may mix legitimate provisions of tax law with false claims.
For example, some promoters reportedly claim there is an agreement involving the Treasury Department, Department of the Interior or tribal governments that allows tribal trust fund payments to be converted into federal tax credits. The IRS says no such agreement exists.
Others point to legitimate transferable tax credits. Federal law does allow certain clean-energy tax credits to be transferred between taxpayers, but the IRS says those provisions don't create a Tribal Tax Credit.
Promoters may also invoke the New Markets Tax Credit, executive orders or the sovereign status of tribal entities. The IRS says none of those provisions create the tax credit being marketed.
Another sales pitch is that other taxpayers have successfully claimed the credit and had their returns accepted by the IRS. But the agency warns that simply accepting and processing a return doesn't mean the IRS has determined that every credit claimed on it is legitimate.
Red flags to watch for
The IRS says consumers should be especially skeptical when someone offers to sell a tax credit for substantially less than its supposed face value.
Other warning signs include claims that only a limited number of credits are available, pressure to act immediately, references to secret or unavailable government agreements and legal opinions that can't be independently verified with the attorney or law firm supposedly providing them.
A request to sign a nondisclosure agreement before receiving basic information about the tax credit is another warning sign. Promoters may also charge fees for arranging the supposed purchase or preparing documentation to support the claim.
The warning fits a broader pattern of tax in which promoters and social media posts promise unusually large refunds based on credits or deductions for which taxpayers aren't eligible. The IRS advises consumers to be suspicious of unsolicited messages promising refunds or tax breaks and of anyone pressuring them for personal or financial information.
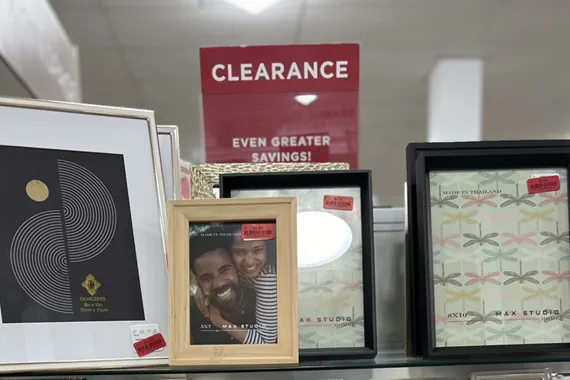
Shop backwards: Check clearance before browsing the rest of the store. You could find a marked-down version of something similar or even identical to what's selling for full price up front.
Know your colors: Red stickers indicate markdowns, while yellow tags are generally used for final-clearance merchandise during major clearance cycles.
Don't blindly wait for a sale: HomeGoods' inventory changes constantly, so waiting for another markdown can mean the chair, lamp, or rug you really want disappears.
HomeGoods is a dangerous place to walk into and say, "I'm just looking."
A $12 candle becomes a $39 lamp, which becomes a $129 chair you had absolutely no intention of buying.
That's partly because HomeGoods doesn't operate like a traditional retailer. Its buyers scoop-up merchandise when manufacturers overproduce or other retailers overbuy. Stores receive new merchandise several times a week, often hundreds of items at a time, and managers may not know what's arriving until the truck shows up.
I've spent years shopping HomeGoods and researching how the chain works, including talking with employees and frequent shoppers about how they find bargains without getting sucked into the treasure hunt.
Here are six strategies that can change the way you shop.
1. Ask when your HomeGoods gets deliveries
Forget the internet advice claiming Tuesday or Wednesday is universally the best day to shop at HomeGoods. There isn't one magic day.
HomeGoods says stores receive new merchandise several times a week. In my own research, I found the more useful strategy is simply asking employees when their particular store typically receives deliveries and when that merchandise usually reaches the sales floor.
That's particularly useful if you're hunting for furniture because employees told me larger pieces tend to get put out quickly.
Ask an employee, "What days do you usually get your biggest deliveries?" Then try shopping shortly after your store typically restocks.
2. Shop backwards
Most shoppers walk into HomeGoods and immediately start browsing whatever is displayed up front.
Try doing the opposite. Head to clearance aisles first, then work your way back toward the front of the store.
One shopper I talked to found a marble cutting board for $12 in clearance, while the same cutting board was priced at $24.99 elsewhere in the store.
Clearance merchandise can also get buried on lower shelves and back-wall endcaps, so don't just scan what's at eye level.
Give clearance a five-minute sweep before doing the rest of your shopping. That way you'll know what's already discounted before considering the full-price stuff.
Pro tip: Decode the four-digit date code. HomeGoods employees have told me that the four-digit number underneath the category on the price tag indicates the month and year the merchandise arrived. For example, 0524 would mean May 2024. That can give you a clue about how long something has been sitting in the store.
3. Learn what the red and yellow price tags mean
Here's one HomeGoods clearance trick that's actually useful: A red sticker indicates an item has been marked down, and you may see multiple markdown stickers on merchandise that has gone through more than one price reduction.
Then there's the elusive yellow tag. Yellow tags represent the final clearance markdown and usually appear during major clearance cycles around January and again during the summer, according to deal trackers and employees.
But don't fall for the social-media hype that a "yellow tag sale" means everything in HomeGoods suddenly gets deeply discounted. Thats just not how it works.
The smart move: Think red = clearance and yellow = probably the final markdown. If you really want something with a yellow sticker, waiting for another price cut probably isn't much of a strategy.
Dont rely on viral posts claiming you can decode the price tags at HomeGoods to determine exactly when its next markdown is coming. While employees have consistently described the four-digit code as the month and year an item arrived, claims online that other tag codes can predict exactly when the next markdown will happen are much shakier.
4. Don't wait for a markdown on something you really love
This sounds contradictory after telling you to hunt for clearance deals first, but it's one of the most important HomeGoods shopping rules.
Waiting only works if the merchandise sticks around, and a lot of the good deals simply dont.
Employees have told me that stores don't keep replenishment inventory sitting in the back, and because individual locations receive thousands of constantly-changing items, they have no way of tracking down how much of a certain product they have in-stock. That means the one chair you're considering may really be the only one of its kind in the entire building.
Its fine to gamble on another markdown when it's something you'd be perfectly willing to lose. But if it's unique, hard to replace, and already a good value, waiting another few weeks could cost you the item rather than save you money.
5. Find the flaw then ask about it
Before buying furniture, lamps, mirrors, or other dcor, inspect them from every angle. Look for scratches, chips, dents, missing hardware, and other damage.
If you find something, don't automatically put it back. Instead, show an employee the specific defect and politely ask whether the item qualifies for an additional markdown.
What you shouldn't do is rely on online claims that a damaged item automatically gets you 10% off, 20% off, or some other specific discount. HomeGoods doesn't publish a guaranteed damage-discount schedule.
Rather than asking, "Can you give me a discount?" try something like: "I noticed this chip on the corner. Does this qualify for a damage markdown?"
Pro tip: Ask for a markdown lookup. If an item looks like it's been sitting around forever but still has its original price, politely ask an employee whether they can do a markdown lookup. HomeGoods employees on Reddit say items can occasionally miss a markdown if they're in the wrong area when markdowns are done or are returned afterward.
6. Google Lens it before assuming it's a bargain
This might be my favorite HomeGoods trick because it takes about 30 seconds.
Lets say you find a lamp, mirror, or cookware item and are wondering if the price is a real deal. Heres what you do: photograph it and run the image through Google Lens or another reverse-image search.
It can quickly identify the item and show prices from other sellers, so you'll know if that $79.99 HomeGoods price is actually a bargain.
One shopper I interviewed found a lamp at HomeGoods for $59 and discovered the same lamp selling at a boutique for $180 using this hack.
But the trick works the other way, too. She considered an $80 mirror until an image search turned up a similar version online for $42. She left the HomeGoods mirror behind.
The smart move is to not let the "Compare At" price make the decision for you. A 30-second image search can tell you whether you've actually found a steal.

 of ConsumerAffairs